Friday, February 14, 2014

REPOST: Planning For An Uncertain Life Expectancy In Retirement

This Forbes.com discusses the importance of setting realistic goals in retirement.

When figuring out how much to save for retirement or how to withdraw assets during retirement, one of the thorniest issues is not knowing how long the individual is going to live. Living longer than expected, which is often referred to as longevity risk, can increase the likelihood of other risks occurring, driving up certain retirement expenditures such as long-term care costs. For those moving into retirement, this is particularly tricky because part of the planning must include a way to secure an adequate stream of income for an unpredictable length of time. For example, let’s say that you build your retirement plan expecting to live to age 82. However, it turns out that you live to 92. How are you going to make your money last an additional 10 years?

The uncertainty of an individual’s lifespan cannot be eliminated. However, planning to have sufficient assets requires setting realistic expectations of how long retirement will last. According to the Social Security Commission, the average life expectancy for those still alive at age 65 is 84 for males and 86 for females. Planning, however, needs to take into consideration living longer than average, or half of retirees could run out of money before they die. So another consideration is the possibility of living longer than average. The data shows that one in four people alive at age 65 will live past age 90 and one in ten will live past 95.

To help identify the average life expectancy for a stated age and gender, the Social Security Administration provides a life expectancy calculator. The calculator indicates that a 60 year old male born in 1953 has an average life expectancy of 83.4 years. If that same person lives to age 66, life expectancy extends to 84.6. Furthermore, if he lives to age 70, his life expectancy extends to age 86. This demonstrates a critical point about life expectancy—the longer you live, the longer your life expectancy. This means that as people age they need to alter their expectations about the length of their life and retirement.

Estimating life expectancy may begin with a table or calculator, but the next step must take into consideration personal and family health history. One online calculator, the living to 100 Calculator, takes these personal factors into consideration when creating a life expectancy estimate. By entering information about your current health, lifestyle habits, and family’s health history, the calculator is able to create a more accurate personal life expectancy estimate.

Solutions for an Uncertain Lifespan

Since planning requires making educated choices about an uncertain retirement period, many will want to plan to age 90, as one in four people are expected to live that long. However, fewer may want to plan for living past age 95, as only one in ten people are expected to live that long. Those with a greater concern about outliving their assets will choose a longer planning horizon. As such, an individual’s perceived life expectancy and risk aversion will impact his or her retirement planning decisions.

One common strategy for all types of risk management is to transfer the risk to a third party. Transferring the risk of living too long can be accomplished by increasing or acquiring sources of lifetime income. This can be accomplished through a variety of mechanisms:

Deferring Social Security benefits, which are an inflation protected lifetime income stream, up to age 70 results in a larger portion of one’s retirement income that will be payable for life.

Electing life annuity payments from an employer sponsored retirement plan will provide lifetime income. Unfortunately, most employees who have the option to take a lump sum make this election, forgoing the annuity alternatives.

Purchasing a life annuity can create a stream of income for either the life of a single individual or over the joint lives of a couple. Immediate annuities can be purchased at retirement or layered over time adding flexibility.

Purchasing a deferred income annuity (a life annuity that begins at a later date) allows for the pre-purchase of lifetime income for those that want to build retirement income prior to retirement or want to buy an annuity that begins later in life, which can be a cost effective way to protect against longevity risk.

Deferred annuities can also be used to create income for life, as these can be annuitized at a later date, allowing the owner to lock in lifetime income. Deferred annuities can be purchased with riders that provide for lifetime withdrawals at a rate specified in the contract. Lifetime income is also available through life insurance contracts. When a death benefit becomes due, a spouse can choose a life annuity form of payment. Also, cash value life insurance contracts can be exchanged under code section 1035 without tax consequences for a life annuity. While increasing sources of lifetime income is one strategy to protect against longevity risk, there are other options when planning for an uncertain retirement time period. As such, some sources of income are payable for an indefinite period of time, which can provide some protection from longevity risk without specifically having to set aside the assets for the sole purpose of lifetime income.

With reverse mortgages under the Home Equity Conversion Mortgage program (HECM) one of the withdrawal options is the tenure option. This is a specified monthly payment for as long as the last borrower remains in the home.

Rental income can provide a lifetime income stream and serve other purposes as well. That could be renting out a basement apartment, vacation home, or commercial property.

Dividend paying stock has no time limit on the payment of dividends and can provide lifetime income, potential investment gains, and company ownership rights.

Those with active business interests can also receive ongoing payments. This can be anything from owning part or all of a company to receiving royalties from books, television shows, or other property interests.

For retirees who fund their living expenses with withdrawals from their portfolio, it is important to carefully consider how much can be withdrawn each year while still ensuring the portfolio lasts a lifetime. This is a difficult decision that should involve consideration of academic research, professional assistance, an individual’s goals and risk tolerance, and changes in market conditions over time.

Another option is the use of a contingency fund, which can be built to address longevity concerns as well as other risks. With this approach, it is important to understand that when individuals live longer they increase exposure to other risks as well, such as inflation risk, public policy risk, and the risks associated with aging, such as the need for long-term care and increased medical expenses. Accordingly, a contingency fund should be part, but not all of the solution.
  • A contingency fund for this risk can be a diversified portfolio with investments that emphasize long-term growth.
  • A Roth IRA makes a good tax wrapper for this type of account since the value is not diminished by taxes, and if the funds are not needed, the Roth is a very tax efficient vehicle to leave funds to heirs.
  • A contingency fund could also be the cash value of a life insurance policy—i.e., the goal may be to provide the death benefit for heirs, but if needed the cash value can be withdrawn or borrowed from the policy.
  • A reverse mortgage with a line of credit payout option is another good contingency plan.
Ultimately, the uncertain length of retirement and longevity risk make planning for retirement extremely difficult because the retiree must have income to meet an uncertain amount of expenditures over an uncertain time period. While this risk cannot be completely eliminated, it can be planned for and managed through a variety of techniques, financial products, and planning strategies.

Isidor Hefter holds a Bachelor’s degree in accountancy, which he completed at the City College of New York. More updates in the world of finance can be found by visiting this Facebook page.

Wednesday, January 8, 2014

REPOST: Making It Safe for Banks to Take (Legal) Pot Money

Read about the banks effort to be able to safely process payments from people or companies involve in marijuana. Bloomberg.com

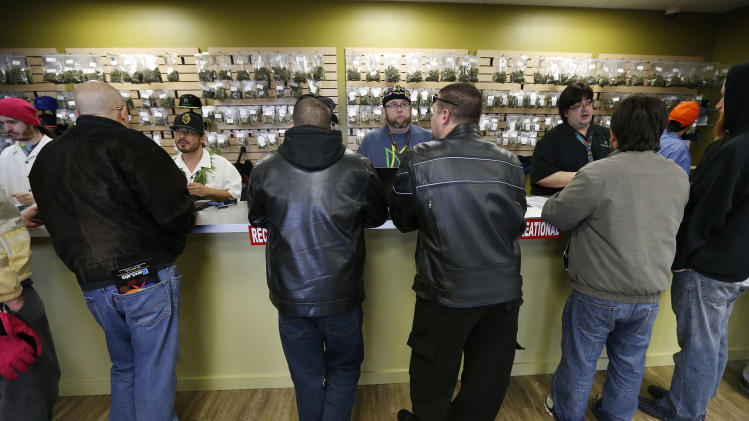
Image Source: Yahoo.News

Colorado’s pot sellers are open for businesses and enjoying brisk sales since recreational marijuana became legal under state law on New Year’s Day. What those stores do with the revenue they bring in, however, is a different question—one that’s gaining salience and attention as more and more legal pot businesses open up shop.

Anti-money laundering rules forbid banks from processing payments or holding accounts for businesses that deal in drugs that remain illegal under federal law. That has left pot businesses forced to operate largely in cash, hauling bags of bills in to pay state taxes and manage their books. As marijuana legalization spreads, with Washington State permitting recreational use and additional states embracing medical uses, more businesses will face this cash conundrum.

The governors of Colorado and Washington have pressed federal bank regulators to let financial institutions open accounts for businesses that follow the state’s pot regulations, and yesterday the Denver City Council passed a resolution (PDF) “urging swift federal action to provide guidance for banking and other financial institutions to serve legal marijuana businesses.”

They are seeking clarity in the banking world similar to what the U.S. Justice Department has already provided by saying it generally won’t pursue criminal drug cases against businesses or users following state laws. In August, the DOJ said that it could decide to bring cases if a situation violates any of eight conditions, such as failure to prevent sales to minors or to customers who illegally resell pot across state lines.

The Justice Department is already working on a memo to provide some guidance for banks, the Wall Street Journal reports. Whether one will provide enough clarity for banks to feel comfortable isn’t yet clear. Other agencies involved in the discussion include the Financial Crimes Enforcement Network, the Federal Deposit Insurance Corp., the Federal Reserve Board, the Office of the Comptroller of the Currency, and the National Credit Union Administration.

Meanwhile, Bob Hasewaga and three other Washington State senators have submitted a bill to create a state-run bank that would be the sole depository for Washington’s marijuana businesses. Hasegawa acknowledges that the bill is a long shot, but he argues that pot businesses need a solution. “They are hoping against hope that the Treasury Department and the financial regulators are going to come up a letter similar to what the U.S. attorney general produced,” he says. “The only alternative right now is cash-based, which is totally unacceptable and cannot adhere to the attorney general’s guidelines because it can’t track every last dollar.”

Isidor Hefter is a senior partner at Rosen Seymour Shapss Martin & Company LLPholds with over 20 years of experience. To know more about him, visit this Facebook page.

Thursday, December 5, 2013

REPOST: Corporate reputation influences tax strategy


Corporate global tax planning and strategy are heavily influenced by its reputation.  This Forbes article explains why and how.  Read the article below: 


Perhaps it was the sight of some of the most well-known company CEOs testifying before Congress on the details of their global corporate tax strategies. Or, maybe it was the widely disputed Government Accountability Office (GAO) report on corporate tax rates that called out U.S. corporations for paying an average 13% tax rate in 2010. Whatever the specific impetus, the outcome is clear: reputation is increasingly becoming a factor that influences corporate tax strategy.

Image source: Forbes.com

We recently raised this topic to a panel of corporate tax experts representing some of the world’s largest accounting firms at our annual SYNERGY 2013 client conference and got some real-world insight into the challenges large companies are currently confronting when it comes to managing their global tax planning, a process heavily influenced by global supply chains and associated transfer pricing compliance. KPMG’s Rema Serafi explained:

“The transfer pricing environment is currently facing a perfect storm. Increased tax scrutiny combined with increased media attention around tax planning has magnified attention on transfer pricing. Interestingly, while there continues to be a focus on the pricing strategy, there is now increased focus on how pricing policies are implemented for accounting purposes. Stakeholders now include tax authorities, regulators, internal audit and  external auditors. Concern about getting the implementation right has moved from the tax department to the C- suite. CFOs, legal departments, risk controllers and those responsible for regulatory matters are now just as concerned about transfer pricing as tax departments. As such, companies are looking for more efficient ways to implement accurately by looking at technology solutions, among other things.”
She’s right. Governments and NGOs around the world, like the OECD, G20, UN and World Bank, are getting involved in the debate over global corporate tax strategies. Meanwhile, companies are facing increased tax complexity as they continue to expand in emerging markets and audits are on the rise. Add the fact that many established economies around the world have been running budget deficits since the recession and you start to see why, suddenly, just about everyone is interested in international taxes.
Hadley Leach, a partner with Ernst & Young LLP, cited the results of a recent survey her firm conducted¸ which found that 66% of companies identified “risk management” as their highest priority for transfer pricing, which was a 32% increase over surveys conducted in 2007 and 2010.  She added:

“There has definitely been a trend toward more conservatism among corporations on international tax strategy. We’re seeing a huge shift in perception around issues of reputational and audit risk and that’s really starting to affect how companies approach tax planning.”
It appears that evolving tax policies, including efforts by the OECD, are going to push harder to ensure that there’s substantive value creation assigned within countries where companies are reporting revenue, and therefore paying tax.
The clear consensus among all of the participants in our panel was that perception has become a serious factor driving corporate tax strategy. The current focus on international tax is rapidly becoming less about limiting tax exposure and more about limiting reputational risk exposure. As Serafi summed it up: “The optics matter.”
As companies continue to move in this direction, expect to see more collaboration between the tax department, finance, accounting and the CFO and more demand for company-wide synchronization of tax policy, global strategy and corporate message.

Isidor Hefter is a senior partner at Rosen Seymour Shapps Martin & Company LLP and specializes in tax planning for corporate and high-net-worth individuals.  Get more materials about tax planning by visiting this Facebook page.


Wednesday, November 6, 2013

Avoiding big surprises on tax day


Image Source:money.msn.com


Thorough preparation is the way to avoid surprises and this applies to the approaching tax day, which is just a few months away. Those who haven’t started on tax planning need to work quickly and accomplish more in a shorter span of time in order to avoid any stressful situations on the 15th of April.

It is faulty oversight to assume that one’s current tax liabilities mirror the previous year’s if his/her financial situation has changed in the present year. There may also be some changes to tax laws that have been implemented, so scheduling an appointment with a tax expert should be at the top of every business owner and gainfully employed citizen’s priorities right now. In accomplishing this as soon as possible, an individual can buy time for measures to deal with the liability such as starting a savings program or adjusting payroll withholdings.


Image Source: usnews.com


As for the factors that could affect a person’s taxes, the common ones are a change in marital status, buying/selling a house, a job change, and retirement. Each of these situations present many details that a taxpayer needs to know in order to avoid being surprised by a change in their tax liability. For instance, newly married couples would need to analyze how their joint finances rearrange their fiscal obligations. In analyzing two sets of data, couples can find out if there are items from which they could derive rebates or if they’ll need to pay more during tax day.


Image Source: quizzle.com


Isidor Hefter is a certified public accountant and a senior partner at Rosen Seymour Shapss Martin & Company LLP who specializes in tax planning and research. Find more articles about year-tax planning through this Twitter page.

Friday, October 4, 2013

Prime time to begin tax planning

For most people, the start of the last quarter of the year marks the beginning of the countdown to the holiday season. However, before thinking about vacations and merrymaking, taxpayers from all income brackets must first put some tax-planning strategies in place to reduce their liabilities for the year.

Image Source: livemint.com

While the deadline for getting things done is still a few months away, investors and tax payers need ample time to assess their current financial situation, re-evaluate their goals, and plan out what needs to be done to stay on track for the next year. They should also check for any changes in the rates and tax cuts that are applicable to them.

Image Source: bridalguide.com

Many taxpayers make the mistake of assuming that their liability from the previous years will apply to their latest tax bill. However, it is wrong to assume that the tax bill will be the same on a year with significant tax law changes. For instance, it is especially important for high income earners to take into consideration in their tax planning the tax cuts from the Bush-era which expired this year.

Image Source: silverplanet.com

With just a little over two months until the new year, taxpayers seeking to keep more of their money need act soon to ensure that their financial planning duties are properly dealt with so as not to interfere with their holiday celebrations.

Isidor Hefter is a certified public accountant and a senior partner at Rosen Seymour Shapss Martin & Company LLP. Find more tax planning advice on this Facebook page.

Saturday, September 7, 2013

REPOST: Ways Professional Traders Can Save Big At Tax Time


Let this Forbes.com article help you learn the mistakes that traders and tax preparers make before planning and filing taxes, and how to avoid them.

Trader tax laws and benefits are complex and nuanced. Far too many traders and tax preparers don’t know the laws or misapply them on tax returns. Why pay tens of thousands of tax dollars more than you should?

Trader Stephen V. Mara of Quattro Securities, ...
Image Source: forbes.com
wise to do the same before planning and filing tax returns. To help with the latter, I’ve assembled a list of the most common mistakes made by traders and tax preparers.

Big picture items

1. Not claiming trader tax status, business expense treatment. (Or claiming this status when not entitled to it.) Business traders can save an average of $5,000 or more using business expense treatment. Business expenses are 100% deductible from gross income, whereas investment expenses are considered miscellaneous itemized deductions and are only deductible “below the line” in excess of 2% of adjusted gross income (AGI) and added back for the Alternative Minimum Tax (AMT), also known as the nasty second tax regime. Business expenses allow home-office deductions, education expenses, and startup costs, whereas investment expenses do not. Also, traders may claim trader tax status after the fact, including on amended tax return filings for the past three open tax years.

2. Not filing the Section 475 MTM ordinary loss election on securities and getting stuck with the puny $3,000 capital loss limitation, wash sale loss headaches, and extra tax costs. Many traders and accountants mishandle the Section 475 election statement (due by April 15 of the current tax year for existing individuals and partnerships) or they botch perfecting the election on a Form 3115 filing. One mix up can jeopardize ordinary gain or loss treatment. The biggest pitfall for traders is not deducting trading losses when they otherwise could. Section 475 does not apply to segregated investments or Section 1256 contracts when elected on securities only.

Unfortunately, you can’t fix a missed or botched Section 475 election; you need to focus on climbing out of the capital loss carryover hole you dug. You can form a new entity and use the “new taxpayer” exception allowing an internal Section 475 election within 75 days of inception.

3. Making the wrong decision about the forex Section 988 opt-out election and reporting forex incorrectly. Spot and forward forex receives Section 988 ordinary gain or loss treatment (which generally is better than a capital loss limitation). At any time during the tax year, traders are entitled to file an internal “contemporaneous” opt-out election to have capital gains treatment instead. That’s helpful if you have capital loss carryovers. If you trade in major forex currencies and don’t “take or make delivery” of the underlying currency, the opt-out election subjects forex forwards — and we make a case for spot forex too — to the lower Section 1256(g) 60/40 tax rates. That reduces the highest tax rates by 12%!

Forex reporting depends on whether you file the Section 988 opt-out election and whether you qualify for trader tax status. Section 988 without trader tax status is line 21 of Form 1040, and with that status its Form 4797 Part II. Section 988 losses over $50,000 require “tax shelter” Form 8886. Many IRS agents are confused over tax treatment for spot forex, plus forex brokers aren’t supposed to issue 1099-Bs for spot forex. Make sure to read brokers’ tax reports correctly. For example, rollover interest is part of trading gain or loss. If you opt-out of Section 988 and choose Section 1256(g), use mark-to-market at year-end on Form 6781. Thankfully, summary reporting applies on forex.

4. Business traders not forming a trading entity to unlock AGI deductions for retirement plans and health insurance premiums. These AGI deductions can save $2,000 to $17,000 or more in taxes, but sole proprietor retail traders can’t get them in connection with trading gains. By forming a simple pass-through entity like a partnership, LLC, or S-Corp, business traders can take advantage of these deductions.

Tax reporting errors and compliance headaches

5. Reporting trading gains and losses on Schedule C, almost guaranteeing an IRS notice or exam. Items must be reported in the correct place. While business expenses are reported on Schedule C, trading gains and losses are reported on other tax forms like 8949, 6781, and 4797.

6. Using our transfer-of-income strategy incorrectly, or not using it at all. The transfer is executed differently for sole proprietors vs. entities. You need this transfer to unlock the home-office deduction, Section 179 depreciation, and AGI deductions, and to reduce the IRS red flag factors on Schedule C and entities.

7. Using the wrong solution for securities trade accounting and calculating gains and losses incorrectly, especially wash sales. Many traders and preparers botch IRS cost-basis reporting on Form 8949 and the reconciliation with Form 1099-B. Some traders fail to report non-1099-B items like stock options on Form 8949. We recommend TradeLog software to handle this after downloading actual trades, rather than inputting 1099-B information.

8. Botching tax treatment between securities, Section 1256 contracts, forex, ETFs, options, precious metals, foreign futures, and more.

9. Misreporting Section 1256 contracts such as securities on Form 8949 rather than on Form 6781, thereby losing lower 60/40 treatment. Not all brokers report Section 1256 contracts correctly, especially instruments that aren’t clearly designated as such including some E-mini indexes and options on those indexes.

10. Misreporting ETFs and ETF options and not adding Schedule K-1 pass-through income to cost basis. ETFs and ETF options are generally taxed as securities, and commodity ETFs often pass through Section 1256 income or loss on a K-1. Options on commodity ETFs can be considered Section 1256 contracts. It’s a pain to deal with numerous ETF K-1s at tax time.

11. Not filing a 1099-Misc for fees paid to service providers, including you for administration. Sole proprietors or entities paying service providers $600 or more by check or cash must issue a Form 1099-Misc. It’s better to file a 1099-Misc. late subject to a penalty of $50 rather than encourage the IRS to catch you and assess much higher penalties.

12. Misreporting education expenses. Pre-business education expenses — including seminars, trade shows, and travel — are generally not allowed as investment expenses. Education is allowed as a business expense but only if incurred after qualifying for trader tax status. Try to squeeze a reasonable amount of pre-business education into Section 195 startup costs to expense once you achieve trader tax status. Don’t fall prey to those promising better results using dual entity schemes including a C-Corp.

13. Not filing a tax return due to negative income and trading losses. Expect a “jeopardy” (made up) tax assessment notice from the IRS. If you trade securities, the IRS doesn’t see the full picture, even with new cost-basis reporting. The IRS may think you made a lot of money and will hit you with a huge tax bill. Not filing can cause you to lose capital loss carryovers for previous years. With 1099s filed by brokers, there is no place to hide.

14. Mishandling tax notices and IRS exams. Generally, IRS and state agents don’t understand a trading business. It’s not a passive loss activity or hobby loss activity, and various items are reported in different areas with complex and nuanced tax treatment and elections. State tax rules for entities usually make exceptions for trading businesses, but that is not always apparent. Before a tax exam gets out of control, consult with a trader tax expert to get it on the right path.

15. Being non-compliant on FBAR and other foreign tax reporting such as Form 8938 (foreign financial assets). Congress and the IRS are very concerned about tax cheats using offshore bank accounts, structures, and schemes. Not filing foreign bank account reports (FBAR) on time or correctly can be costly: Back taxes, penalties, interest, and even criminal proceedings could be the result. Consider the IRS’s Offshore Voluntary Disclosure Initiative (OVDI). (Note that this program is NOT amnesty; in some cases, it’s a mistake to enter OVDI when there’s a better way to come clean.) Generally, opening offshore entities doesn’t help reduce taxes as they are treated as disregarded entities or they are subject to passive foreign investment company rules. Avoiding the Commodity Futures Trading Commission’s rules for retail forex trading by using offshore accounts or entities doesn’t work.

Entities and retirement plans

16. Forming the wrong type of entity, and in the wrong state. If you live, work, and trade in your home state and want to form a pass-through entity, it’s best to form it there. Don’t fall prey to promoters in Nevada harping on the benefits of corporations formed in Nevada. If you don’t register that Nevada entity in your home state, you won’t have asset protection in your home state. A Nevada LLC filing as a partnership passes through its income to your home state.

17. Tapping into IRA and other retirement funds incorrectly, causing IRS penalties and trouble. Don’t get busted by the IRS for misusing your retirement funds. See our recent blog “Learn the DOs and DON’Ts of using IRAs and other retirement plans in trading activities and alternative investments” for more on this topic.

18. Triggering wash sale losses in IRAs which are permanently lost. Far too many traders make this tragic mistake. When you buy back a “substantially identical” security position in any of your IRAs 30 days before or after selling it for a loss in any of your taxable accounts, you can kiss that tax loss goodbye forever. It applies across husband and wife individual and joint accounts. Normally, wash sales are only a deferral problem, but in this case it’s a permanent problem. Abstain from trading substantially identical positions in your IRA accounts or house your active trading in an entity, which is a different taxpayer for purposes of the wash sale rules. A Section 475 election also solves this problem.

19. Choosing the wrong type of retirement plan. The Individual 401(k) plan for business traders is best. It combines a 100% deductible 401(k) elective deferral — where the biggest tax savings lies — with a 20% deductible profit sharing plan. Don’t forget to open this plan before year-end, even with no money contributed.

20. Paying self-employment (SE) taxes on trading gains. Only full members of futures exchanges owe SE taxes on futures trading gains. Too many traders pay SE taxes on these gains and the IRS doesn’t challenge it. Watch out for the new Affordable Care Act’s 3.8% Medicare surtax on unearned income starting in 2013.

Bottom line

Common mistakes cost traders tens of thousands of dollars per year on their tax returns. Don’t be penny wise and pound foolish. Spend a few dollars to buy premium trader tax guides to learn how to avoid these mistakes. Consider engaging a trader tax expert to help with your tax return elections, planning, and preparation. Use the right trade accounting software for securities. Some mistakes you can fix on tax returns on extension or on amended tax return filings. Other mistakes can’t be fixed, and you should focus on tax strategies to dig out of that hole.

Carrying out year-end tax planning could be a gamble or even a waste of time. To avoid this, follow Isidor Hefter's Twitter page to help you deal with your tax agonies.

Monday, August 5, 2013

REPOST: IBM stands behind cloud-computing account amid SEC probe

Many companies believe that cloud-computing is the future, and IBM is no exception. This AccountingToday.com article reports that the company is standing behind its cloud-computing accounting methods despite the SEC probe.

*****

(Bloomberg) International Business Machines Corp., facing a Securities and Exchange Commission investigation into how it reports revenue from offsite cloud services, said it stands by its accounting methods.

IBM is cooperating with the SEC in the probe, which it learned about in May, it said today in a filing. The company books its revenue from cloud services, such as storing customers’ data and software applications remotely, under generally accepted accounting principles, said Ed Barbini, a spokesman for Armonk, New York-based IBM.

“IBM’s reporting of cloud revenue is the result of a rigorous and disciplined process, and we are confident that the information we have provided has been consistently accurate,” Barbini said.

Chief Executive Officer Ginni Rometty has identified cloud computing as one of IBM’s chief sources of growth amid a slowdown in demand for hardware and for consulting services. The investigation at the company, known for consistently meeting analysts’ earnings estimates, underscores confusion about how cloud revenue should be booked, said Michael Cusumano, a management professor at the Massachusetts Institute of Technology’s Sloan School of Management.

“This is a murky area where the rules aren’t really established,” Cusumano said. “Companies treat cloud-computing revenue in different ways.”

About half of publicly traded software companies since 1990 have had to restate revenue because of misclassification of sales and product returns, or because they categorized ongoing payments for tech-support services as a sale of a product license, Cusumano said.

‘Disciplined Process’
While IBM doesn’t disclose its revenue from cloud services, it said the sales rose 70 percent in the first half of 2013 from a year earlier. In its filing today, the company didn’t provide details on what information the SEC was seeking.

“IBM has robust systems and controls to identify and validate what products and services count as cloud revenue,” Barbini said. “IBM accounts for cloud transactions exactly the same way as it would account for those transactions if they were not cloud—in accordance with GAAP.”

Florence Harmon, an SEC spokeswoman, declined to comment.

IBM has beat analysts’ earnings expectations in 32 of the past 33 quarters, according to data compiled by Bloomberg. On the other hand, it has missed sales estimates in seven of the past eight quarters.

More Probes?
The investigation may be the first in a series of probes into companies in the same industry as the SEC tries to clear up confusion and differences in standards, said Jack Ciesielski, owner of investment firm R.G. Associates Inc. in Baltimore and the publisher of the Analyst’s Accounting Observer.

The company has a goal of reaching $7 billion in cloud revenue by 2015, with about $3 billion from new business and the rest from current contracts shifting over to the cloud category.

IBM’s 70 percent growth rate for cloud-computing services in the first six months of 2013 was a slowdown from 80 percent last year. IBM has also said cloud revenue, which is spread across several divisions, tripled in 2011 from 2010.

IBM shares fell 1 percent to $195.04 at the close in New York. The stock has gained 1.8 percent this year.

The disclosure of the probe comes days after IBM won court approval for a $10 million settlement with the SEC for accusations of bribery in China and South Korea. IBM said earlier this year it’s the subject of a U.S. Justice Department bribery investigation related to contracts in Poland, Argentina, Bangladesh and Ukraine.

Autonomy Writedown
Hewlett-Packard Co., IBM’s archrival in the computer-services business, took an $8.8 billion charge last year to write down the value of Autonomy, a software company it acquired, amid allegations of accounting improprieties within the unit. Autonomy, whose products organize corporate customers’ data, had used aggressive tactics to inflate its results, a former executive told Bloomberg News last year.

Earlier this month, IBM acquired SoftLayer Technologies Inc., a cloud-computing storage provider. IBM paid almost $2 billion for Dallas-based SoftLayer, according to a person familiar with the deal.

Market researcher IDC estimates the cloud-computing market may more than double to $105 billion by 2016 from last year. SoftLayer specializes in public clouds—data-center networks that manage computing and software for businesses remotely. IBM is pairing those capabilities with private-cloud operations, building dedicated systems for individual customers.


More news and tidbits about accounting and taxation can be found by following this Isidor Hefter Twitter page.